

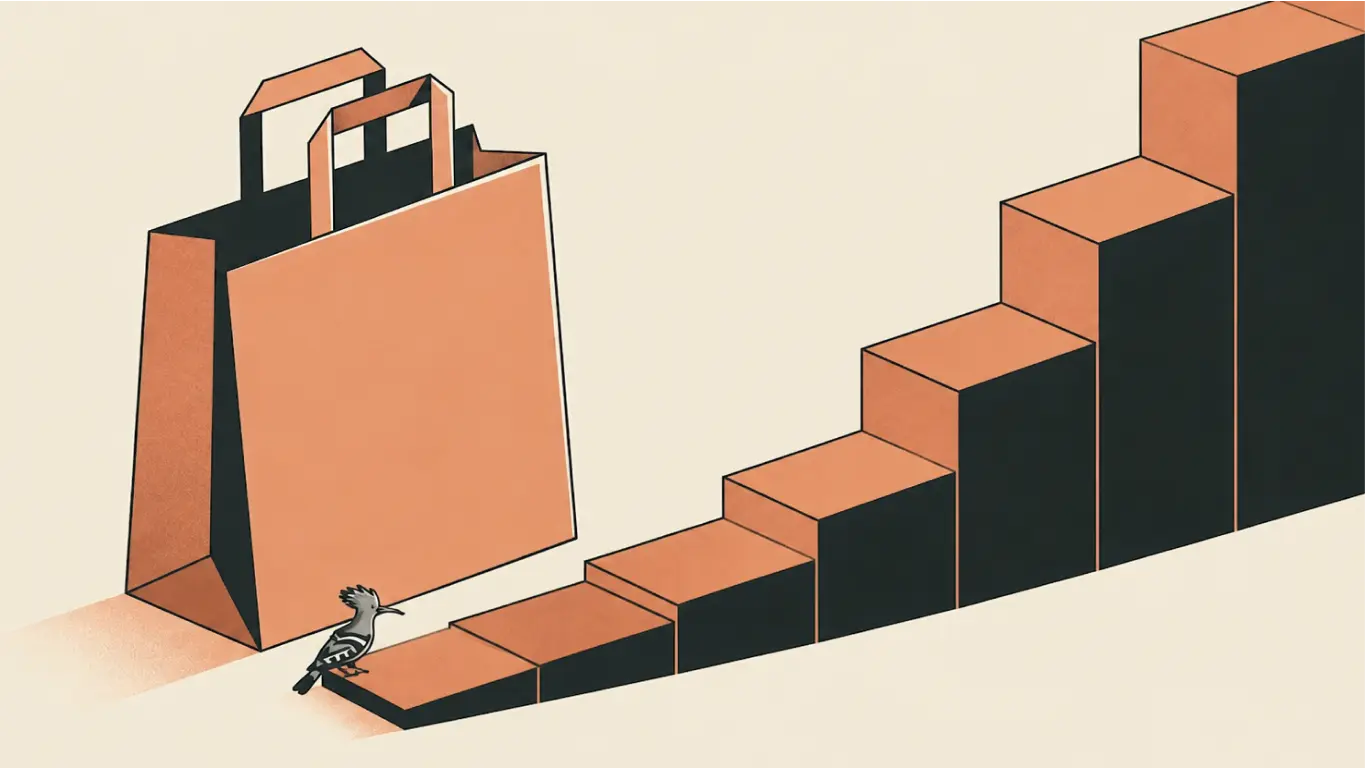
It used to be for appliances. By August 2026, consumer installment finance in Egypt covered electronics and furniture, but also groceries, restaurant meals, travel bookings, healthcare services, school tuition, and even gold. This financial product didn't change categories, it dissolved the lines between them. If something can be sold, it can now be split.
The numbers reflect how fast this happened:
- 3.27 million active clients by end of 2024 vs 10.8 million clients by end of 2025, a 227% increase in a single year
- Over EGP 96.3 billion disbursed in 2025 alone
- Total non-banking finance portfolio: EGP 417 billion
- Default rate: below 3% per the FRA, described by the regulator as within safe and stable limits
But 3% of 10.8 million is still over 300 thousand people in financial difficulty. A small percentage is not a small number. That growth rate makes more sense when you understand where Egypt was starting from:
- Egypt remains a predominantly cash economy, roughly 80% of transactions are conducted in cash
- Personal debt levels are significantly lower than Gulf markets, not because Egyptians are more financially secure, but because formal credit was simply not accessible to most people
- Consumer finance companies moved into that gap deliberately and at scale
- The sector achieved a CAGR of 53% between 2021 and 2024
- Projected to reach USD 4.74 billion by 2030, making Egypt the fastest-growing consumer finance market in North Africa
The regulator's response is worth reading carefully. In 2024, the Financial Regulatory Authority paused the acceptance of new consumer finance company applications and licenses, a freeze that Said Zater, Chairman of the Egyptian Federation of Consumer Finance, publicly endorsed. The stated reason: to reorganize the market, review licensing standards, and ensure the sector's expansion remains sustainable before new entrants are permitted. A regulator that freezes licenses in a fast-growing sector is not celebrating momentum, it is managing risk.
Regulatory update, September 2026: When this article was published in August 2026, gold was still being financed through some consumer-finance channels. On 16 September 2026, the Financial Regulatory Authority directed consumer finance companies to cease transactions involving gold bullion, gold jewelry, and bullion or jewelry made from other precious metals, including silver and platinum. The regulator said these products are investment vehicles, not consumer goods eligible for financing under Consumer Finance Law No. 18 of 2020. The circular made the law’s existing boundary explicit and closed a workaround through which some bullion products designed as wearable jewelry had been presented as financeable goods.
 Conclusion
None of this makes consumer installment finance inherently harmful. Accessible credit, used with discipline and clear-eyed understanding, is a useful financial tool. The question is whether the people using it at scale, 10.8 million and growing, are doing so with that understanding, or simply responding to a product that has been made frictionless and ubiquitous by design. Article 2 looks at how the model actually works, and what the difference is between installment finance done right and installment finance done profitably.
→ Next: How Installment Finance Actually Works: Traditional, Commercial, and Islamic
A product expert, the co-founder, and CEO of Xeer, a personal finance management platform built on Islamic Sharia principles. His work sits where Sharia fintech meets everyday money practices. He writes in Jarida to put financial awareness within reach of every Arabic speaker.
Read also
Navigate Financial Freedom with Chess Mindset
End the cycle of spending guilt and learn how to manage your finances with a simple, stress-free plan.
 6 min read
Your Route to Financial Freedom: A Glossary of the Concepts That Get You There
Financial literacy is one of those phrases that sounds impressive and explains nothing on its own. This article maps the core concepts you need in your toolkit, from opportunity cost to emergency funds, and it is updated continuously.
5 min read
Ramadan: A Practical Reset for Your Financial Habits
Ramadan is meant to be a month of restraint, yet it has quietly become one of the heaviest spending seasons of the year. This article turns the month into a structured reset for your financial habits, from planning the food budget to giving deliberately and leaving Ramadan without new debt.
8 min read
Download the app now!
Read more through the Xeer app. Download it now and enjoy all Xeer features.
 Download the App

Read also
Beyond "BNPL": The Real Cost of Consumer Installment Finance
Consumer installment finance doesn't just affect the people using it, it reshapes spending behavior, market pricing, and economic stability at scale. This article traces the real cost of BNPL from the individual decision all the way to the broader market, and what to do with that understanding.
 Ahmed El Zoughby
8 min read
Traditional Installments & Commercial BNPL through the lens of Islamic Finance
Installment finance in Egypt takes more than one form, and the differences between them are not in the marketing, they're in the structure. This article breaks down some of those commercial models, what each one hides, and where each one stands against the sharia compliance standards.
Ahmed El Zoughby
7 min read
Step-by-Step Guide to Sharia-Compliant Credit Cards
A card carrying the name "Islamic card" is not enough to make it Sharia-compliant; what counts is the contract detail, the repayment mechanism, and how late payment is handled. This guide lays out a clear path to using credit benefits when you need them, without compromising your values.
Ahmed El Zoughby
6 min read